Should you buy salesforce.com stock now?
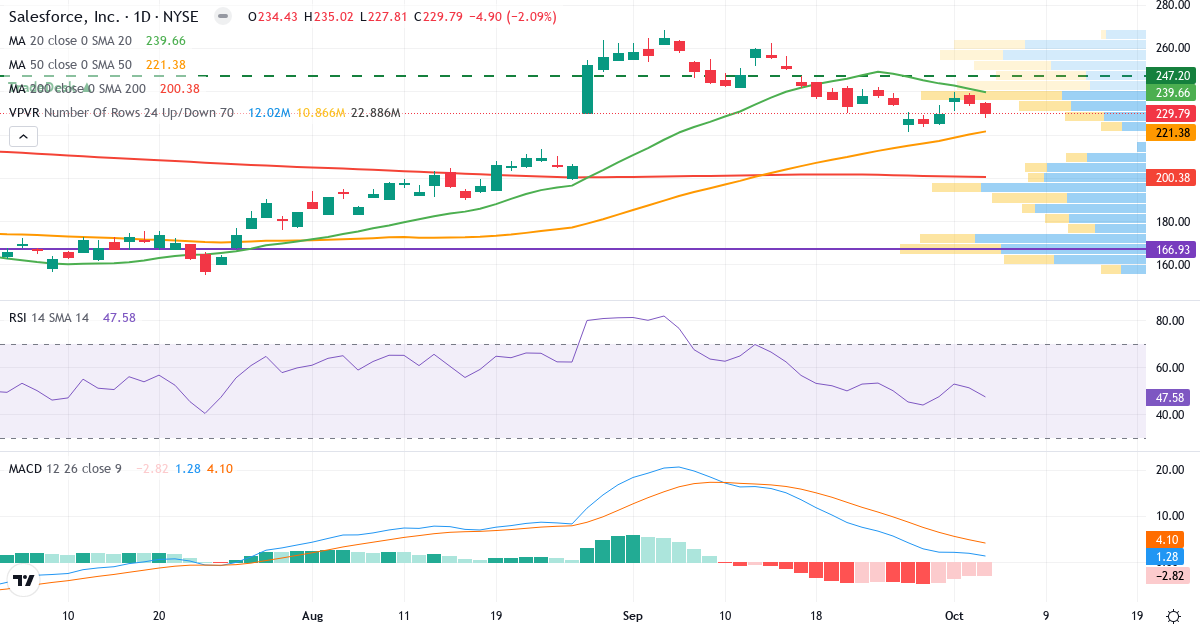
Yes, the technical signal for salesforce.com is currently Strong Buy. salesforce.com trades at $225.15 as of Oct 7, 2026. The technical analysis shows the following: MACD is positive (bullish trend) at 0.528 with falling momentum (signal: 3.457); RSI is at 44.3 (neutral zone); the stock is in a short-term downtrend (price below the 20-day average); the analyst price target of $283.36 points to 25.9% upside. The stock is in a broader uptrend (above SMA50/SMA200). This is a technical observation based on current data, not investment advice.
What is the price target for salesforce.com stock?
The average analyst price target for salesforce.com is $283.36. The current price is $225.15, which gives an upside of 25.9%. Based on this, the stock is considered undervalued. The fair value range (±10% of the price target) is between $255.02 and $311.70.
Is salesforce.com a dividend stock?
Yes, salesforce.com is a dividend stock with a dividend yield of 0.72%. The latest dividend was $0.44 per share. The latest ex-dividend date (traded without the dividend) was Sep 17, 2026. The payout ratio is 10.9%, which is considered sustainable. The next dividend payment is scheduled for Oct 8, 2026.
When does salesforce.com pay a dividend in 2026?
salesforce.com pays its next dividend on Oct 8, 2026. The latest dividend was $0.44 per share with an ex-dividend date of Sep 17, 2026. The dividend yield is 0.72%. The payout ratio of 10.9% points to a sustainable dividend with room to grow.
What is the risk of salesforce.com stock?
salesforce.com is rated as a stock in the risk category Moderate. the annual standard deviation is 47.7%, which classifies the stock as Moderate.
Is salesforce.com overvalued?
No, salesforce.com is considered undervalued based on the analyst price target (25.9% upside). salesforce.com has the following valuation ratios: a P/E ratio of 21.5 (moderately to highly valued), a P/S ratio of 4.4, a P/B ratio of 5.0. The analyst price target suggests that the stock is undervalued by 25.9%.
Is salesforce.com overbought?
No, salesforce.com is not overbought. RSI is at 44.3 (neutral zone). The technical indicators show: RSI is at 44.3 (neutral zone between 30-70), which signals neither overbought nor oversold. In addition, the price is 5.5% below the 20-day average (short-term downtrend). In addition, MACD is positive, but momentum is falling.
When is the next salesforce.com earnings report?
The date of the next earnings report for salesforce.com has not been published yet. Check the company's investor calendar for updates.
Is salesforce.com shorted?
Yes, salesforce.com is shorted with 4.5% of the free float sold short. This is a moderate level of short selling, within the normal range for most stocks. The figure comes from our data provider EODHD, is reported about twice a month, and we check it every trading day.
Are insiders buying salesforce.com stock?
Yes, insiders are net buyers of salesforce.com – they are buying more shares than they are selling. Over the last 3 months, insiders have made 1 purchases and 1 sales. On a net basis, 629,826 $ worth of shares were bought. Across the last 20 reported transactions, the split is 9 purchases and 11 sales, with a net 14,390,028 $ sold. Active buyers include Kirk David Blair, Laura Alber, ALBER LAURA and others. Insider buying is generally seen as a positive signal, because management is putting its own money into the company.
Is salesforce.com a good stock?
Based on our total score, salesforce.com is rated as a mediocre stock with a total score of 55 out of 100. The stock scores around average on value, quality and momentum – it sits near the median in our database. The score is made up of Value: 46/100, Quality: 44/100, Momentum: 76/100. In addition: analysts see 25.9% upside to the price target; a dividend of 0.72%; technical signal: Strong Buy. Whether salesforce.com is a good investment depends on your time horizon, risk profile and portfolio. This is a data-driven observation, not investment advice.
What is the outlook for salesforce.com stock?
The outlook for salesforce.com based on current data: the average analyst price target is $283.36 (+25.9%); the stock is in an uptrend (above SMA50 and SMA200); the P/E ratio is 21.5 (moderate). Keep in mind that stock prices are affected by many factors, including earnings reports, the economy and market sentiment. Past returns are no guarantee of future returns.
Why is salesforce.com stock falling?
salesforce.com is falling right now. The technical indicators show: the price is 5.5% below the 20-day average; insiders have mostly been buying the stock recently. For the latest context, see our technical analysis and insider section above.
How high can salesforce.com go?
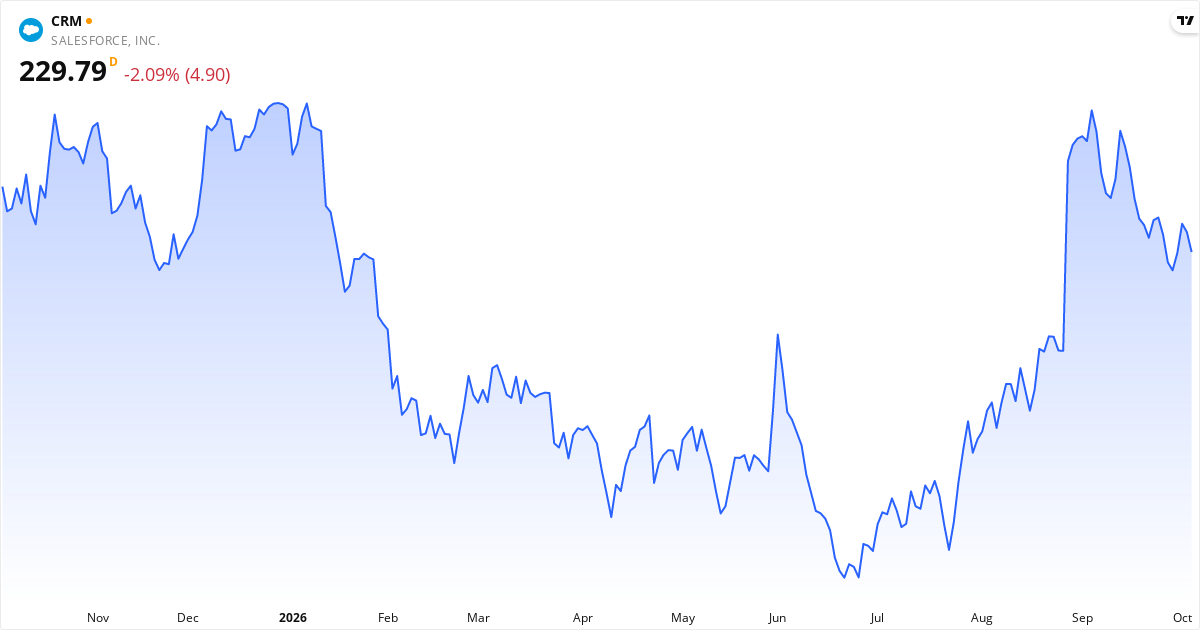
The average analyst price target for salesforce.com is $283.36, which corresponds to a potential gain of 25.9% from the current price of $225.15. The stock has traded between $146.06 and $267.80 over the last 52 weeks. Keep in mind that price targets are estimates, not guarantees. Actual price moves depend on earnings, market conditions and unexpected events.
How low can salesforce.com fall?
The stock has traded as low as $146.06 over the last 52 weeks — that is 35.1% below the current price of $225.15. The biggest decline (drawdown) in the same period was 45.5% from high to low. Within a year, the price typically swings about ±47.7% (standard deviation — a measure of price swings). A difficult year could therefore mean a further decline of that size. Remember: past price swings are no guarantee for the future — a stock can fall further than the last 52 weeks suggest, especially on profit warnings, sector crises or a market crash. Use stop-loss orders and spread your portfolio to limit losses in single stocks.
What does salesforce.com do?
Salesforce makes software that helps companies keep track of their customers. This type of software is called CRM, short for Customer Relationship Management. The company earns money by selling access to a large platform called Customer 360, which connects sales, customer serv... The company belongs to the Technology sector, more specifically the Software - Application industry, is headquartered in United States, and is traded on the USA Stocks. See the key figures, earnings history and price development above to evaluate salesforce.com as an investment.
Did salesforce.com raise or lower its guidance?
Over the last 60 days we have not registered a guidance raise or cut from salesforce.com. The company can still adjust its guidance at quarterly reports or between reports — see the earnings history above.
Is salesforce.com making money or losing money?
Yes, salesforce.com is making money, not losing it. The company has a profit margin (the share of revenue left over as profit) of 22.0% — which is excellent. The operating margin (profit before interest and taxes) is 21.4%. At a P/E ratio of 21.5, you currently pay 21.5 dollars for every dollar of the company's annual earnings. A consistently profitable company is usually more resilient than growth stocks that are not yet making money.
Can salesforce.com go bankrupt?
The bankruptcy risk of salesforce.com is rated as moderate. Altman Z2 (a model for assessing financial distress) is 1.90 — that places the company in the middle zone. The Piotroski score (financial health 0-9, higher is better) is 4 — which is average. Debt relative to equity is 68% (moderate). Remember: models like Altman Z2 are statistical — unexpected shocks (fraud, a sector collapse, lawsuits) can always happen. Spread your portfolio.
Does salesforce.com have a lot of debt?
salesforce.com has moderate debt relative to equity. The debt-to-equity ratio (D/E — interest-bearing debt to equity) is 68%. For the technology sector, 60-120% counts as a typical level. Tech companies are usually asset-light and need little borrowed capital — anything below 60% counts as low in this sector. Note: D/E levels are highly sector-specific — a bank at 300% debt is normal, a tech stock at 300% is extremely leveraged. Always compare with similar companies in the same sector. Can salesforce.com service its debt? Can service its debt without problems — the interest coverage ratio (how many times earnings can cover interest payments) is 10.6x, and net debt equals 2.6 years of earnings (EBITDA).